
Download AICPA : CPA-Regulation Questions & Answers as PDF & Test Software

Last Updated: Sep 10, 2026
No. of Questions: 70 Questions & Answers with Testing Engine
Download Limit: Unlimited
Reliable & Actual Study Materials for CPA-Regulation Exam Success
Our Online Test Engine & Self Test Software of TestSimulate CPA-Regulation actual study materials can simulate the exam scene so that you will have a good command of writing speed and time. Then multiple practices make you perfect while in the real AICPA CPA-Regulation exam. The package practice version will not only provide you high-quality CPA-Regulation exam preparation materials but also various studying ways.
100% Money Back Guarantee
TestSimulate has an unprecedented 99.6% first time pass rate among our customers.  We're so confident of our products that we provide no hassle product exchange.
- Best exam practice material
- Three formats are optional
- 10 years of excellence
- 365 Days Free Updates
- Learn anywhere, anytime
- 100% Safe shopping experience
- Instant Download: Our system will send you the products you purchase in mailbox in a minute after payment. (If not received within 12 hours, please contact us. Note: don't forget to check your spam.)
AICPA CPA-Regulation Practice Q&A's

- Printable CPA-Regulation PDF Format
- Prepared by CPA-Regulation Experts
- Instant Access to Download
- Study Anywhere, Anytime
- 365 Days Free Updates
- Free CPA-Regulation PDF Demo Available
- Download Q&A's Demo
AICPA CPA-Regulation Online Engine

- Online Tool, Convenient, easy to study.
- Instant Online Access
- Supports All Web Browsers
- Practice Online Anytime
- Test History and Performance Review
- Supports Windows / Mac / Android / iOS, etc.
- Try Online Engine Demo
AICPA CPA-Regulation Self Test Engine

- Installable Software Application
- Simulates Real Exam Environment
- Builds CPA-Regulation Exam Confidence
- Supports MS Operating System
- Two Modes For Practice
- Practice Offline Anytime
- Software Screenshots
From your first practice test to the day you book the exam, TestSimulate covers the whole AICPA Certified Public Accountant CPA Regulation journey: 70 regularly updated questions, three study formats, 365 days of free updates, and a conditional money back guarantee. For busy professionals in 2026, one reliable source of CPA-Regulation preparation beats a dozen half-finished resources.
AICPA CPA-Regulation Exam Overview:
| Certification Vendor: | AICPA |
|---|---|
| Exam Name: | Uniform CPA Examination - Regulation (REG) |
| Exam Number: | REG |
| Real Exam Qty: | 76 MCQs + 8 TBS |
| Exam Format: | Multiple Choice Questions (MCQ), Task-Based Simulations (TBS) |
| Certificate Validity Period: | 18–30 months (varies by state/jurisdiction rules, typically 30 months credit window) |
| Related Certifications: | CPA Audit (AUD) CPA Business Environment and Concepts (BEC replaced under CPA Evolution with ISC/TCP disciplines) CPA Financial Accounting and Reporting (FAR) |
| Available Languages: | English |
| Exam Price: | Approx. 250–350 USD (varies by jurisdiction) |
| Exam Duration: | 240 minutes |
| Passing Score: | 75 |
| Recommended Training: | AICPA CPA Exam Resources |
| Exam Registration: | CPA Exam Official Information |
| Sample Questions: | AICPA CPA-Regulation Sample Questions |
| Exam Way: | Computer-based testing at authorized Prometric test centers |
| Pre Condition: | No formal prerequisite, but eligibility is determined by individual US state Board of Accountancy requirements (education and credit-hour requirements typically required to sit for CPA Exam). |
| Official Syllabus URL: | https://www.aicpa-cima.com/cpa-exam |
AICPA CPA-Regulation Exam Syllabus Topics:
| Section | Weight | Objectives |
|---|---|---|
| Federal Taxation of Entities | 15–25% | - S corporations - Partnerships - Estate and trust taxation basics - C corporations taxation |
| Federal Taxation of Individuals | 15–25% | - Individual tax computations - Deductions and credits - Gross income inclusions and exclusions |
| Ethics, Professional Responsibilities and Federal Tax Procedures | 15–25% | - Ethical and professional responsibilities - Federal tax procedures |
| Business Law | 20–30% | - Contracts - Business structure and regulation - Commercial transactions (UCC) - Agency |
| Federal Taxation of Property Transactions | 5–15% | - Basis calculations - Property disposition and recognition of gain/loss |
Common Questions About the AICPA CPA-Regulation Exam
The CPA-Regulation exam is the official AICPA exam behind AICPA Certified Public Accountant CPA Regulation — passing it earns you the Certified Public Accountant (CPA) certification, a credential positioned at the Professional level. It is built for candidates who want to validate the skills measured by AICPA Certified Public Accountant CPA Regulation. Depending on your track, the exam is also linked to the CPA Audit (AUD), CPA Financial Accounting and Reporting (FAR) and CPA Business Environment and Concepts (BEC replaced under CPA Evolution with ISC/TCP disciplines) certifications, so one pass can move you toward more than one AICPA credential.
The CPA-Regulation exam presents 76 MCQs + 8 TBS questions to be completed within 240 minutes. That pace leaves little room for second-guessing: read each question carefully on the first pass, flag the ones you want to revisit, and keep moving instead of stalling on a single item. Before exam day, run at least one full timed session in the TestSimulate desktop or online test engine with a comparable question load — a steady rhythm under the clock is a trainable skill, and it is often what separates a pass from a near miss.
To pass the CPA-Regulation exam you need 75, and the official registration fee is Approx. 250–350 USD (varies by jurisdiction). Keep in mind that a failed attempt means paying that fee again in full — retakes are not discounted. Given the cost, self-test before you book: if you can score comfortably above the passing mark on two or three consecutive timed TestSimulate practice tests, your budget is far better spent on the exam itself than on a retake.
No formal prerequisite, but eligibility is determined by individual US state Board of Accountancy requirements (education and credit-hour requirements typically required to sit for CPA Exam). Because AICPA revises its certification programs from time to time, treat this as a starting point rather than the final word. Confirm the current eligibility requirements on the official AICPA exam page before you register.
Registration for the CPA-Regulation exam is handled through the official channels below:
Delivery method: Computer-based testing at authorized Prometric test centers — pick the option that suits you best when booking your slot.
AICPA points AICPA Certified Public Accountant CPA Regulation candidates toward the following official courses:
Official courses build the foundation; pairing them with the 70 CPA-Regulation practice questions from TestSimulate turns that knowledge into exam-day readiness.
Yes. A free PDF demo of the CPA-Regulation practice questions is available, so you can check the question style and answer quality before spending anything. Every purchase also includes 365 days of free updates — whenever AICPA adjusts the AICPA Certified Public Accountant CPA Regulation blueprint, your material is refreshed at no cost during that period. After the first year, you can extend the update service at a 50% discount from your member zone.
TestSimulate backs your purchase with a 100% Money Back Guarantee. If you take the corresponding exam within 60 days of purchase and do not pass, you can claim a full refund by submitting a scanned copy of your exam enrollment slip together with the official Score Report PDF within 2 days of your exam date; approved claims are processed within 7 days. The guarantee applies only to the exam matching your purchase, the candidate name must match the payer name, and it does not cover attempts taken within 3 days of purchase, candidates who downloaded the material but never sat the exam, expired orders, or free materials. If you would rather keep preparing, you can exchange the product for two free exam preparation packages of equal value and keep the update service on your original purchase.
Delivery is instant: your download is available right after payment, and a copy is emailed to you within one minute. If nothing arrives within 2 hours, check your spam folder and contact our support team. There is no limit on the number of computers you can install the software on.
The AICPA Certified Public Accountant CPA Regulation syllabus is organized into 5 domains. Among the headline areas are Federal Taxation of Property Transactions (5–15%), Ethics, Professional Responsibilities and Federal Tax Procedures (15–25%), Federal Taxation of Individuals (15–25%). Rather than copying every subtopic here, we keep the complete, current outline in the Exam Topics section above — work through it domain by domain with the TestSimulate CPA-Regulation practice questions so nothing on the blueprint catches you off guard.
AICPA Certified Public Accountant CPA Regulation Sample Questions:
Which of the following statements is the best definition of real property?
- A. Real property is only land.
- B. Real property is land and everything permanently attached to it.
- C. Real property is all tangible property including land.
- D. Real property is land and intangible property in realized form.
Explanation: Only visible for TestSimulate members. You can sign-up / login (it's free).
Hall, a divorced person and custodian of her 12-year old child, filed her 1990 federal income tax return as head of a household. She submitted the following information to the CPA who prepared her
1990 return:
* The divorce agreement, executed in 1983, provides for Hall to receive $3,000 per month, of which
$600 is designated as child support. After the child reaches 18, the monthly payments are to be reduced to $2,400 and are to continue until remarriage or death. However, for the year 1990, Hall received a total of only $5,000 from her former husband. Hall paid an attorney $2,000 in 1990 in a suit to collect the alimony owed.
* In June 1990, Hall's mother gifted her 100 shares of a listed stock. The donor's basis for this stock, which she bought in 1970, was $4,000, and market value on the date of the gift was $3,000. Hall sold this stock in July 1990 for $3,500. The donor paid no gift tax.
* During 1990, Hall spent a total of $1,000 for state lottery tickets. Her lottery winnings in 1990 totaled $200.
* Hall earned a salary of $25,000 in 1990. Hall was not covered by any type of retirement plan, but contributed $2,000 to an IRA in 1990.
* In 1990, Hall sold an antique that she bought in 1980 to display in her home. Hall paid $800 for the antique and sold it for $1,400, using the proceeds to pay a court-ordered judgment.
* Hall paid the following expenses in 1990 pertaining to the home that she owns: realty taxes,
$3,400; mortgage interest, $7,000; casualty insurance, $490; assessment by city for construction of a sewer system, $910; interest of $1,000 on a personal, unsecured bank loan, the proceeds of which were used for home improvements. Hall does not rent out any portion of the home.
What amount should be reported in Hall's 1990 return as alimony income?
- A. $5,000
- B. $36,000
- C. $0
- D. $28,800
Explanation: Only visible for TestSimulate members. You can sign-up / login (it's free).
Doris and Lydia are equal partners in the capital and profits of Agee & Nolan, but are otherwise unrelated. The following information pertains to 300 shares of Mast Corp. stock sold by Lydia to Agee
& Nolan: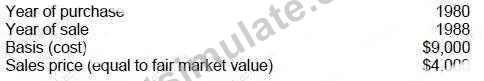
The amount of long-term capital loss that Lydia realized in 1988 on the sale of this stock was:
- A. $5,000
- B. $2,500
- C. $3,000
- D. $0
Explanation: Only visible for TestSimulate members. You can sign-up / login (it's free).
Tom and Joan Moore, both CPAs, filed a joint 1994 federal income tax return showing $70,000 in taxable income. During 1994, Tom's daughter Laura, age 16, resided with Tom. Laura had no income of her own and was Tom's dependent.
Determine the amount of income or loss, if any that should be included on page one of the Moores'
1994 Form 1040.
During 1994, the Moores received a $2,500 federal tax refund and a $1,250 state tax refund for 1993 overpayments. In 1993, the Moores were not subject to the alternative minimum tax and were not entitled to any credit against income tax. The Moores' 1993 adjusted gross income was $80,000 and itemized deductions were $1,450 in excess of the standard deduction. The state tax deduction for
1993 was $2,000.
- A. $75,000
- B. $55,000
- C. $1,300
- D. $2,000
- E. $25,000
- F. $10,000
- G. $2,500
- H. $900
- I. $1,500
- J. $3,000
- K. $1,000
- L. $1,250
- M. $500
- N. $0
- O. $50,000
Explanation: Only visible for TestSimulate members. You can sign-up / login (it's free).
Tom and Joan Moore, both CPAs, filed a joint 1994 federal income tax return showing $70,000 in taxable income. During 1994, Tom's daughter Laura, age 16, resided with Tom. Laura had no income of her own and was Tom's dependent.
Determine the amount of income or loss, if any that should be included on page one of the Moores'
1994 Form 1040.
In 1992, Joan received an acre of land as an inter-vivos gift from her grandfather. At the time of the gift, the land had a fair market value of $50,000. The grandfather's adjusted basis was $60,000. Joan sold the land in 1994 to an unrelated third party for $56,000.
- A. $75,000
- B. $55,000
- C. $1,300
- D. $2,000
- E. $25,000
- F. $10,000
- G. $2,500
- H. $900
- I. $1,500
- J. $3,000
- K. $1,000
- L. $1,250
- M. $500
- N. $0
- O. $50,000
Explanation: Only visible for TestSimulate members. You can sign-up / login (it's free).
 Tyrone
Alice
Celeste
Emily
Irene
Linda
Myra
TestSimulate is the world's largest certification preparation company with 99.6% Pass Rate History from 74033+ Satisfied Customers in 148 Countries.

Over 74033+ Satisfied Customers


